

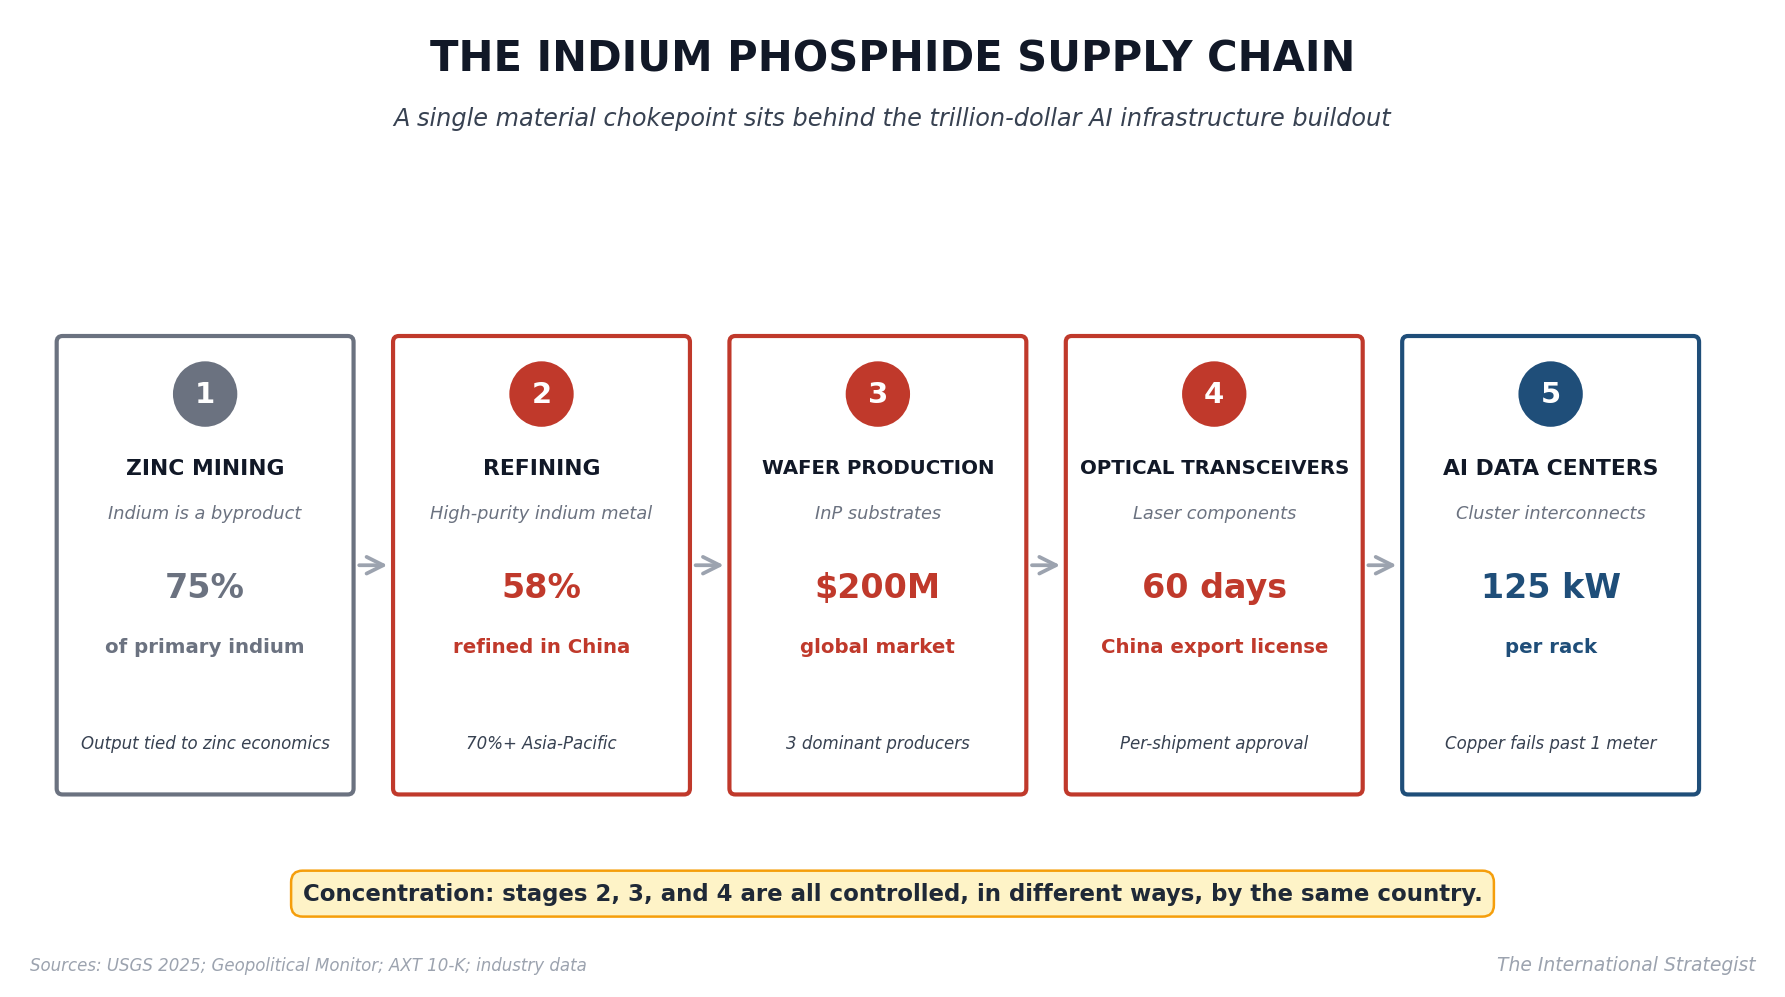
The AI infrastructure buildout is not being slowed by transistor density. It is not being slowed by GPU supply. It is being slowed by a $200 million wafer market dominated by three Asian countries, governed by a Chinese export license that takes 60 business days to process.
The material is indium phosphide. Until two years ago, almost no policymaker outside of compound semiconductor manufacturing had heard of it. Today, it sits between every advanced AI cluster and the data those clusters need to move. Beijing has noticed. Washington is starting to.
This is the story of how a byproduct of zinc smelting became the most strategically consequential semiconductor material of the AI era, and what its supply structure now means for the competition that will shape the next decade.
What changed inside the data center
Compute capacity has always been the headline number in the AI race. Nvidia’s H100s. Then the B200s. Then GB200 NVL72 racks. Each generation increases the per-chip throughput. The race has been about chips.
It is now about what connects the chips.
Training a frontier large language model is no longer a problem that one server can hold. It requires tens of thousands of GPUs, often hundreds of thousands, all processing fragments of the same calculation in parallel. The bottleneck is not how fast each chip runs. It is how fast the chips can talk to each other.
At the data rates modern AI clusters require, 224 gigabits per second per lane in industry standard hardware shipped through 2025, copper cables cease to function past roughly one meter. Signal integrity collapses. Power loss climbs. The physics simply do not allow it.
Optical fiber works. Light moves through glass at roughly 200,000 kilometers per second with losses measured in fractions of a decibel per kilometer. But optical fiber requires a transceiver at each end. The transceiver requires a laser that produces light at telecommunications wavelengths. Silicon cannot do this. Gallium arsenide can do it imperfectly. Only indium phosphide does it efficiently at the scales modern data centers demand.
A single rack of advanced AI hardware now draws up to 125 kilowatts. That is more than an average American household uses in a month, in one rack. Cluster scale-up requires optical interconnect fabrics so dense that the substrate inside every transceiver becomes a system-level constraint.
That substrate is indium phosphide.
The supply chain is the strategic weapon
Indium is not mined. It is recovered from zinc.
Roughly 75% of global primary indium supply comes as a byproduct of zinc smelting. The economics of indium production are therefore not driven by indium demand. They are driven by zinc prices. When zinc smelters reduce output, indium output falls regardless of how much the AI industry will pay for it.
The refining concentration is severe. China produces 58% of refined indium globally. South Korea, Japan, and Canada follow. The combined Asia-Pacific share of global production is over 70%. Western refining capacity outside Canada is minimal.
The wafer market is even more concentrated. The global indium phosphide wafer market was valued at approximately $200 million in 2025. The market is dominated by three companies: Sumitomo Electric in Japan, AXT in China (manufacturing in Beijing), and a handful of smaller specialty producers. There are no scaled producers in Europe or the United States. Coherent operates a Texas facility funded by a recent $33 million US government investment. Lumentum is expanding production in North Carolina. Both efforts are real. Neither is at production scale yet.
This is the strategic weapon. A material the AI industry cannot do without, refined predominantly in one country, processed into wafers by three Asian manufacturers, with zinc economics constraining how fast supply can grow even if every Western government decided today to underwrite a new domestic industry.
The Chinese decision was deliberate
On February 4, 2025, China imposed export controls on indium and four other materials, including the explicit restriction on indium phosphide substrates and the precursor chemicals needed to manufacture them.
The licensing regime is the lever. Every shipment requires Ministry of Commerce approval. AXT, which manufactures indium phosphide wafers in Beijing for export to global customers, reports that licenses take approximately 60 business days to process. The applicant must submit detailed end-user information for every shipment, which serves a dual intelligence purpose. Beijing now knows exactly which Western customers depend on the material, and at what volume, before issuing each license.
The price response was immediate. Indium prices climbed from $2,600 per kilogram in January 2025 to $3,000 within weeks of the announcement. By March 2026, the price had reached $4,700 per kilogram. That is an 81% increase in 14 months.
When the November 2025 US-China trade deal lifted most rare-earth and critical mineral restrictions in exchange for tariff reductions, Beijing kept indium phosphide on the controlled list. The selectivity is the message. China is willing to negotiate over most leverage points. It is not willing to give up the one that sits inside the AI infrastructure buildout.
What this means for the data center timeline
The constraint is already binding.
Coalition for a Prosperous America research, drawing on Sightline Climate data, indicates that almost half of US data centers planned for 2026 are expected to be delayed or canceled. Transformer shortages, switchgear shortages, and battery supply constraints are the visible causes. Indium phosphide is a less visible cause, but it is real. AXT reported that lead times for high-purity InP source materials extended from 8-12 weeks to 16-20 weeks during 2024, before the export licenses added another 60 business days.
The strategic implications are not abstract. AI capability is increasingly a function of cluster size. Cluster size is increasingly a function of optical interconnect availability. Optical interconnect availability is increasingly a function of how fast a Chinese ministry processes export paperwork.
The market response is underway but inadequate. AXT is doubling indium phosphide capacity through 2026 and again through 2027. Sumitomo is expanding. Lumentum and Coherent are building US-based capacity with federal support. AXT’s CEO has been explicit that 2026 order demand could double, then double again in 2027, then inflect upward in 2028-2029 as co-packaged optics adoption accelerates.
None of this changes the upstream concentration in refined indium. Adding more wafer producers does not add more refined indium feedstock. The bottleneck moves up the chain.
The Indian position is a structural blind spot
India is on every list. The National Critical Mineral Mission, approved in January 2025 with a total outlay of ₹34,300 crore including PSU contributions, identifies indium as one of 30 critical minerals. India’s Semiconductor Mission has approved multiple fabrication and assembly units. The strategic intent is real.
The capability is not.
India produces no refined indium. It has no domestic indium phosphide wafer manufacturing. The fabrication units under the Semiconductor Mission are designed for silicon wafers, not compound semiconductors. India’s exposure is complete: every indium-bearing component in every Indian-built electronic system passes through a Chinese or Korean or Japanese supplier.
This is not a uniquely Indian problem. Every Western economy faces the same architecture. The difference is that the United States has a Defense Production Act and a Lumentum expansion underway. India has a list.
The strategic question for New Delhi is whether the National Critical Mineral Mission produces operational refining capacity in time to matter. Mission funding through 2030-31 is roughly $4 billion including PSU contributions. The US Project Vault stockpiling initiative alone is $12 billion. The Indian mission has to do everything Project Vault does, plus build refining capacity that exists nowhere else outside East Asia, on one-third the budget.
What to watch
Three signals will indicate whether the chokepoint widens or eases.
The November 27, 2026 trade truce expiration. When the current US-China critical minerals suspension expires, Beijing will choose what to extend, what to harden, and what to release. Indium phosphide is the most likely material to be hardened rather than released. If the licensing regime is tightened further, the AI infrastructure timeline for 2027 gets worse, not better.
AXT’s STAR Market listing on the Shanghai exchange. AXT, the China-based wafer producer with US ownership, is pursuing a listing of its Tongmei subsidiary in China. If Beijing approves the listing on favorable terms, Chinese capital becomes the primary backer of the company that sets the global price for the wafer. If Beijing slow-walks the listing, AXT’s US shareholders bear the cost. Either outcome tells you who Beijing thinks holds the leverage.
Whether Lumentum’s North Carolina facility reaches production scale in 2026. If it does, the United States has a domestic alternative for the first time. If it slips, Western dependence on East Asian wafers continues for the rest of the decade.
The AI race is described as compute versus compute, model versus model, hyperscaler versus hyperscaler. Underneath, it is a contest over a $200 million material extracted as a byproduct of zinc mining, refined in three countries, fabricated by three companies, and licensed for export by one government.
That government is not the one building the data centers. It is the one deciding how fast they can be built.
Excellent read